What Financial Information Should You Keep Alongside a Will? UK Guide
Reviewed internally for accuracy by SuccessionKeeper: October 2026
In short: a will sets out how you want your estate dealt with after your death, but it is not normally a current inventory of every bank account, pension, investment, insurance policy and important document you hold. Your executor may therefore know what your legal instructions are without knowing which organisations to contact or where the information needed to administer the estate is held.
A separate, private financial record can fill that gap. At a minimum, it should show where the original will is stored, which banks, pension schemes, investment providers and insurers you use, which professional advisers may need to be contacted and where relevant documents can be found. It does not need to contain passwords, PINs or bank login details. Even among people who have already made a will, our UK Financial Preparedness Survey 2026 found that only 42% said their partner would find locating all their accounts and documents very easy, and only 50% said their partner was fully aware of all their accounts and where they were held.
A Will Can Be Complete While the Financial Picture Is Not
Making a will is one of the clearest steps a person can take to prepare for what happens after their death. It can identify executors, specify beneficiaries and explain how an estate should be distributed. GOV.UK's guidance on making a will on making a will explains the basic position and notes that different rules apply in Scotland and Northern Ireland.
The difficulty is that a will answers only part of the practical question an executor eventually faces. Imagine the will says the estate should be divided equally between two children. That is a clear legal instruction, but the executor still has to work out what makes up the estate: which banks, which pensions, which investments, which insurance policies and which professional advisers were involved. A well-drafted will does not necessarily answer any of those questions, because that is not its primary job.
MoneyHelper'sguidance on getting your finances in order recommends making sure an executor has a full list of bank accounts, savings, investments, insurance policies and other financial products, together with provider contact information, and keeping important documents somewhere an executor or loved one can find them.
What Financial Information Should You Keep Alongside Your Will?
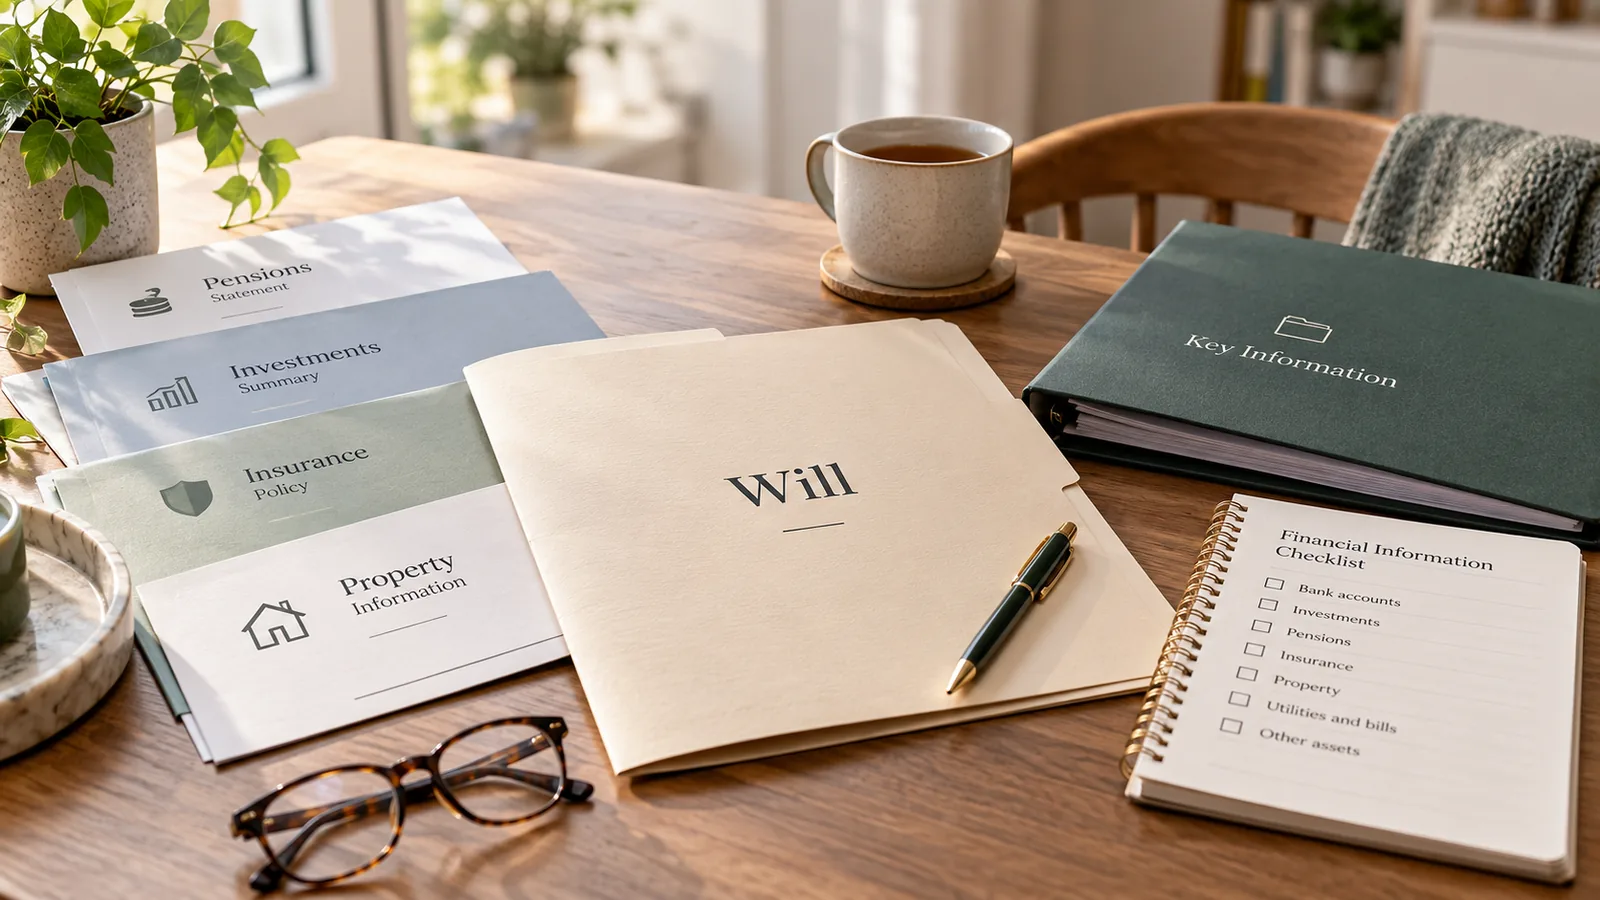
The aim is not to reproduce your entire financial life on paper. It is to preserve enough information that somebody starting without you can identify the organisations involved and know where to look next. A useful record would normally cover the following.
· Your will and legal documents: where thesigned original will is stored, the date of the current version, who holds itand where any Lasting Power of Attorney or trust documentation can be found.
· Executors and professional contacts: yourexecutors, solicitor, accountant, financial adviser or other relevantprofessional, together with current contact information.
· Banking and savings: the banks andbuilding societies you use and the type of account held with each provider.
· Investments: ISA providers, investmentplatforms, brokers, funds or other investment relationships.
· Pensions: workplace and personal pensionproviders, the employer associated with each workplace pension and a member orpolicy reference if you choose to record one.
· Insurance: life insurance, relevantemployer-provided cover and other policies that somebody dealing with youraffairs may need to identify.
· Property: properties owned, mortgageproviders and where relevant title, mortgage or insurance information is held.
· Other significant financial relationships: PremiumBonds and other NS&I products, business interests, overseas assets andother accounts that may not be obvious from everyday household finances.
· Liabilities: mortgages, loans or othersignificant debts where somebody administering the estate would need to knowwhich organisation to contact.
· Document locations: where supportingstatements, policy schedules, property records and other material are stored.
You do not need to record current balances. Account numbers can be included if you are comfortable doing so, but they do not need to be mandatory for the record to be useful. Passwords, PINs, authentication codes and private keys serve a different purpose. The useful question is not "could somebody log in as me?" It is "would they know this account existed and which organisation to contact?"
Should You Put Your Bank Accounts in Your Will?
For most people, a will is not the best place to maintain a changing list of banks, account numbers and current balances. Your financial life may change several times while the legal intentions expressed in your will remain exactly the same. You might close one savings account, open another, move an ISA or consolidate an investment account without changing who you want to inherit your estate.
A signed will cannot simply be edited each time that happens. GOV.UK's guidance on updating a will explains that amendments require a formal codicil, signed and witnessed in the appropriate way, or a new will for more significant changes, and recommends reviewing a will every five years and after major life events.
There is also a privacy consideration. In England and Wales, probate records can be searched after probate has been issued, and a copy of a probate record can include the will where there is one, as the GOV.UK probate search service confirms. That does not make a will unsafe; it simply means that a will is not the natural place to maintain detailed account references or credentials.
What Is the Difference Between a Will and a Financial Inventory?
A will deals with authority and instructions. A financial inventory deals with discovery and context. The inventory cannot override a will or give anybody legal authority to deal with an account, and legal authority does not automatically give an executor knowledge of every organisation involved. MoneyHelper's guide to dealing with an estate makes clear that estate administration involves identifying the deceased person's assets before they can be valued and distributed.
An executor who knows that the deceased banked with Barclays, held an ISA with Vanguard, had a workplace pension from an earlier employer and used Legal & General for life insurance has several concrete places to begin. An executor who knows only that "everything goes to the children" still has to discover the estate.
What About a Lasting Power of Attorney?
A will deals with what happens after death. A Lasting Power of Attorney deals with what happens if you lose the capacity to manage your own affairs during your lifetime. The two documents serve different legal purposes, but they share one practical requirement: whoever acts under them needs to know what exists before they can act on it.
An attorney appointed under a Property and Financial Affairs LPA has legal authority to deal with your bank accounts, pensions, investments and property on your behalf. That authority is of limited use if the attorney does not know which bank, which pension provider or which investment platform you use. The financial inventory serves the attorney in the same way it serves an executor, by providing the discovery and context that the legal authority itself does not provide.
For families where mental capacity may become a concern through age, illness or injury, keeping a current record of financial relationships is particularly useful. The attorney does not need the record on the day the LPA is signed, but they need to know it exists and where to find it when the time comes.
What Assets May Not Pass Under Your Will?
There is a second reason the record sitting alongside your will should be broader than the will itself. Some important financial arrangements may operate under their own rules. Property is a good example. GOV.UK's joint property ownership guidance explains that property can be held either as joint tenants or tenants in common, and that the type of ownership affects what happens when one owner dies. A share held as joint tenants passes to the surviving owner rather than being disposed of through the will, while a share held as tenants in common can pass under the will.
Pensions also require separate consideration. Many pension schemes operate on a discretionary basis, and MoneyHelper's guidance on pensions after death explains that trustees or pension providers will commonly consider an expression-of-wish nomination, although they may retain discretion over the eventual recipient. Life insurance can create another route: where a policy has been placed in trust, the proceeds can be paid to the people chosen under the trust without first passing through the ordinary probate process.
Because the legal route can differ from the will, it is particularly useful to record that the pension, insurance policy, trust or jointly owned asset exists and where the relevant documentation can be found.
Why Pension Information Is Becoming Even More Important
Pension information is particularly easy to fragment because a working life can create a separate pension relationship every time somebody changes employer. If the provider behind an old workplace pension is later forgotten, the family may first have to reconstruct employment history before they can even establish which scheme to contact. Our guide How to Find Lost Pensions in the UK sets out the tracing process.
The issue takes on additional administrative significance from 6 April 2027, when most unused pension funds and pension death benefits will be brought within the value of the deceased's estate for Inheritance Tax purposes, with personal representatives taking responsibility for the relevant reporting and tax process. We cover those changes in Pensions and Inheritance Tax From April 2027.
Where Should You Keep Your Will?
The signed original will needs to be stored securely, and your executor must also know where it has been stored. Common options include storage at home, with a solicitor, through a will-writing service, or through the Probate Service in England and Wales, as set out in MoneyHelper's guide to storing your will. The key practical point is to write down where the original is stored and give that information to the executor rather than relying on a conversation that may have happened years earlier.
How Should the Financial Inventory Itself Be Stored?
A financial inventory is only useful if someone else can find it when the time comes. A comprehensive record kept in a drawer that nobody knows about, on a laptop that nobody can unlock, or in a folder on an email account that is closed when the account holder dies achieves nothing.
The practical options vary in how findable they make the record. A printed copy stored at home works if a trusted person knows where to look. An encrypted document on a laptop works if someone knows the login details and the file location. One of the most reliable approaches is to keep the inventory alongside the signed will at the office of the solicitor, will writer or estate planner who already holds it, because the family would already have reason to contact that professional and the record is passed on through an existing route rather than a separate one.
For the same reason, the contact details of the lawyer, estate planner or will writer who holds the record should themselves be known to the family, or kept somewhere easily found. A professional who cannot be identified cannot pass on anything they hold. A specialist service designed for this purpose, such as SuccessionKeeper, offers an alternative that combines encrypted storage with a controlled process for the record to reach nominated contacts without them needing login details. Whichever option you choose, what matters is that the record exists in a form someone else can reach, and that the person who would need it knows where to look.
What Should You Keep Out of the Record?
A financial inventory should make accounts findable without becoming a substitute for a password manager or a way around a provider's security process. There is no need for somebody to know your bank password in order to know that you bank with HSBC. They do not need your pension-provider login to know that an Aviva pension exists. They do not need your investment-platform authentication code to know which institution should eventually be contacted by somebody with the appropriate legal authority.
That distinction also protects the integrity of the estate-administration process. An executor, attorney or family member still has to establish their authority with each organisation and follow its own verification procedures. The inventory provides the map; it does not provide the keys. For a broader breakdown of what is useful to record, see our Digital Accounts Inventory Checklist.
When Should You Review Your Will and Financial Record?
The two records should both be kept current, but they do not need to be updated on the same timetable. GOV.UK recommends reviewing a will every five years and after significant life changes such as getting married, having a child, moving house, separation or divorce, or the death of the executor named in the will. Formal changes require the appropriate legal process rather than handwritten amendments.
A financial inventory can be more fluid. Opening or closing an account, changing jobs, acquiring another pension, moving an investment, buying property, changing insurer or changing solicitor can all justify a quick update even when the will itself remains entirely appropriate. Your legal intentions may remain stable for years; the institutions holding your financial life may not.
How SuccessionKeeper Can Help
SuccessionKeeper is a private record of where your accounts, pensions, policies and documents are held, so someone you trust knows where to start. Alongside your accounts, you can record where the original will is stored, which solicitor holds it, which insurers and investment providers you use and where supporting documents can be found. Provider names and account types are enough to begin; account numbers, balances, notes and documents are optional. There are no bank connections, and bank or provider passwords are not required or stored. You can read more on How SuccessionKeeper Works.
What to Do After You Sign or Update Your Will
Once the legal document is signed, it is worth asking a different question from the one you asked while writing it. Do not ask only whether the will says what you want it to say. Ask whether somebody following those instructions would know where to begin.
Could your executor find the signed original? Would they know which banks, pensions and insurers to contact? Could they identify your solicitor or financial adviser? If those answers are clear, the will is backed by a practical record that can help somebody use it. If they are not, the missing step may not be another legal document. It may simply be the map.
Key Terms Explained
Will. A legal document setting out what should happen to your money, property and possessions after death. GOV.UK explains that a valid will in England and Wales must satisfy formal requirements including writing, signature and witnessing.
Executor. The person or people appointed to administer an estate and carry out the terms of the will.
Beneficiary. A person or organisation entitled to receive something under a will or another financial arrangement.
Probate. The process through which an executor may obtain the legal authority required to deal with an estate. In England and Wales, probate records can subsequently be searched through the government's probate-record service.
Codicil. A formal alteration to an existing will, which must be signed and witnessed in the same way as a will.
Intestacy. The legal position that arises when somebody dies without a valid will, leaving statutory rules to determine who inherits.
Joint Tenants. A form of joint property ownership under which the surviving owner or owners automatically continue to own the property after one owner dies. The deceased person's interest cannot be left to somebody else in their will.
Tenants In Common. A form of property ownership under which each owner has a separate share. That share can pass under the owner's will.
Expression Of Wish. A pension nomination indicating who the scheme member would like to receive pension death benefits. In many discretionary schemes the provider or trustees take the nomination into account but retain the final decision.
Financial Inventory. A private record showing which financial relationships, accounts, pensions, policies and important documents exist and where they are held. It does not distribute assets, grant legal authority or replace a will.
Lasting Power of Attorney. A legal document through which a person appoints one or more attorneys to make specified decisions on their behalf. An LPA and a will serve different legal purposes.
Frequently Asked Questions
What financial information should I keep with my will?
Keep a separate private record showing which financial providers you use, including banks, savings providers, pensions, investments and insurers, together with relevant property information, important liabilities, professional contacts and the location of significant documents. The record should also say where the signed original will itself is held.
Should I list all my bank accounts in my will?
For most people, a separate private financial record is more practical than trying to maintain a changing account list inside the will. Financial providers can change without your wishes about inheritance changing, whereas changes to a signed will require a formal process.
Should I put bank passwords or PINs in my will?
A will should not be treated as a password repository. The practical information an executor needs initially is that an account exists and which institution holds it. The bank itself will determine what evidence and authority it requires before dealing with the executor.
Where should I keep my financial inventory?
Somewhere a trusted person can reach it when needed. Common options include a printed copy stored with your signed will at a solicitor, will writer or estate planner, an encrypted document on your own computer, or a specialist service designed for this purpose. Whichever option you choose, the people who may one day need the record should either know where it is or be able to find out easily.
What information does my executor or attorney need?
Both an executor acting after death and an attorney acting under an LPA need enough information to identify and reach the relevant financial providers, including banks, savings, investments, pensions, insurance, property and professional contacts. Legal authority on its own is not enough; the person acting also needs to know what exists.
Does my will cover my pension?
Not necessarily in the same way as ordinary estate assets. Pension death benefits commonly follow scheme rules, and an expression-of-wish nomination may be relevant. You should therefore record every pension provider separately even if the pension is not ultimately distributed under the terms of the will.
Related Reading
Digital Accounts Inventory Checklist: What to Record andWhy It Matters
How to Find Bank Accounts After Death in The UK
How to Find Lost Pensions in The UK
How to Talk To Ageing Parents About Money, Wills andFinancial Accounts
Pensions and Inheritance Tax from April 2027
UK Financial Preparedness Statistics 2026
Sources
GOV.UK, Joint Property Ownership
GOV.UK,Make, Register or End a Lasting Power of Attorney
MoneyHelper, How to Get Your Finances in Order Before YouDie
MoneyHelper, Where to Store Your Will and How to TellYour Executor
MoneyHelper, What to Do When Someone Dies and Leaves aWill
MoneyHelper, Pensions Help After Someone's Death
HMRC, Inheritance Tax on Pensions: Technical Note 2, 27August 2026
SuccessionKeeper, UK Financial Preparedness Survey 2026
About The Author
Peter Vulchev, CFA, is co-founder of SuccessionKeeper, a private financial inventory that helps people keep track of what they have and where it is held, so someone they trust knows where to start if needed. He spent his career in investment management, including roles at BlackRock and within the investment advisory teams of Apollo and Lone Star Funds, before building SuccessionKeeper with co-founder Deyan Nenov.
This article is for general information only and does not constitute legal, tax, financial, pension or estate-planning advice. It focuses principally on England and Wales. Scotland and Northern Ireland have different legal systems and rules governing wills, succession and estate administration, so readers in those jurisdictions should use the relevant official guidance or obtain professional advice. If you are making or changing a will, have a blended family, own assets overseas, own a business, want to establish a trust or have any uncertainty about how your estate should be structured, consider obtaining advice from a suitably qualified solicitor. SuccessionKeeper does not provide legal, financial, tax or pension advice. It does not replace a will, Lasting Power of Attorney, trust or professional adviser.